For years, the industry has said a small share of VCs makes most of the returns globally. Now LPs are acting on it.
In 2026, established firms took 88.2% of all US venture fundraising. That’s the highest share PitchBook has ever recorded.
a16z alone closed $23.8B. That’s more than 1 in every 5 dollars raised in US venture this year.
As Eric Newcomer argues, AI’s huge capital needs are pushing the megafund model to its limits. They’re also concentrating power in a handful of firms.
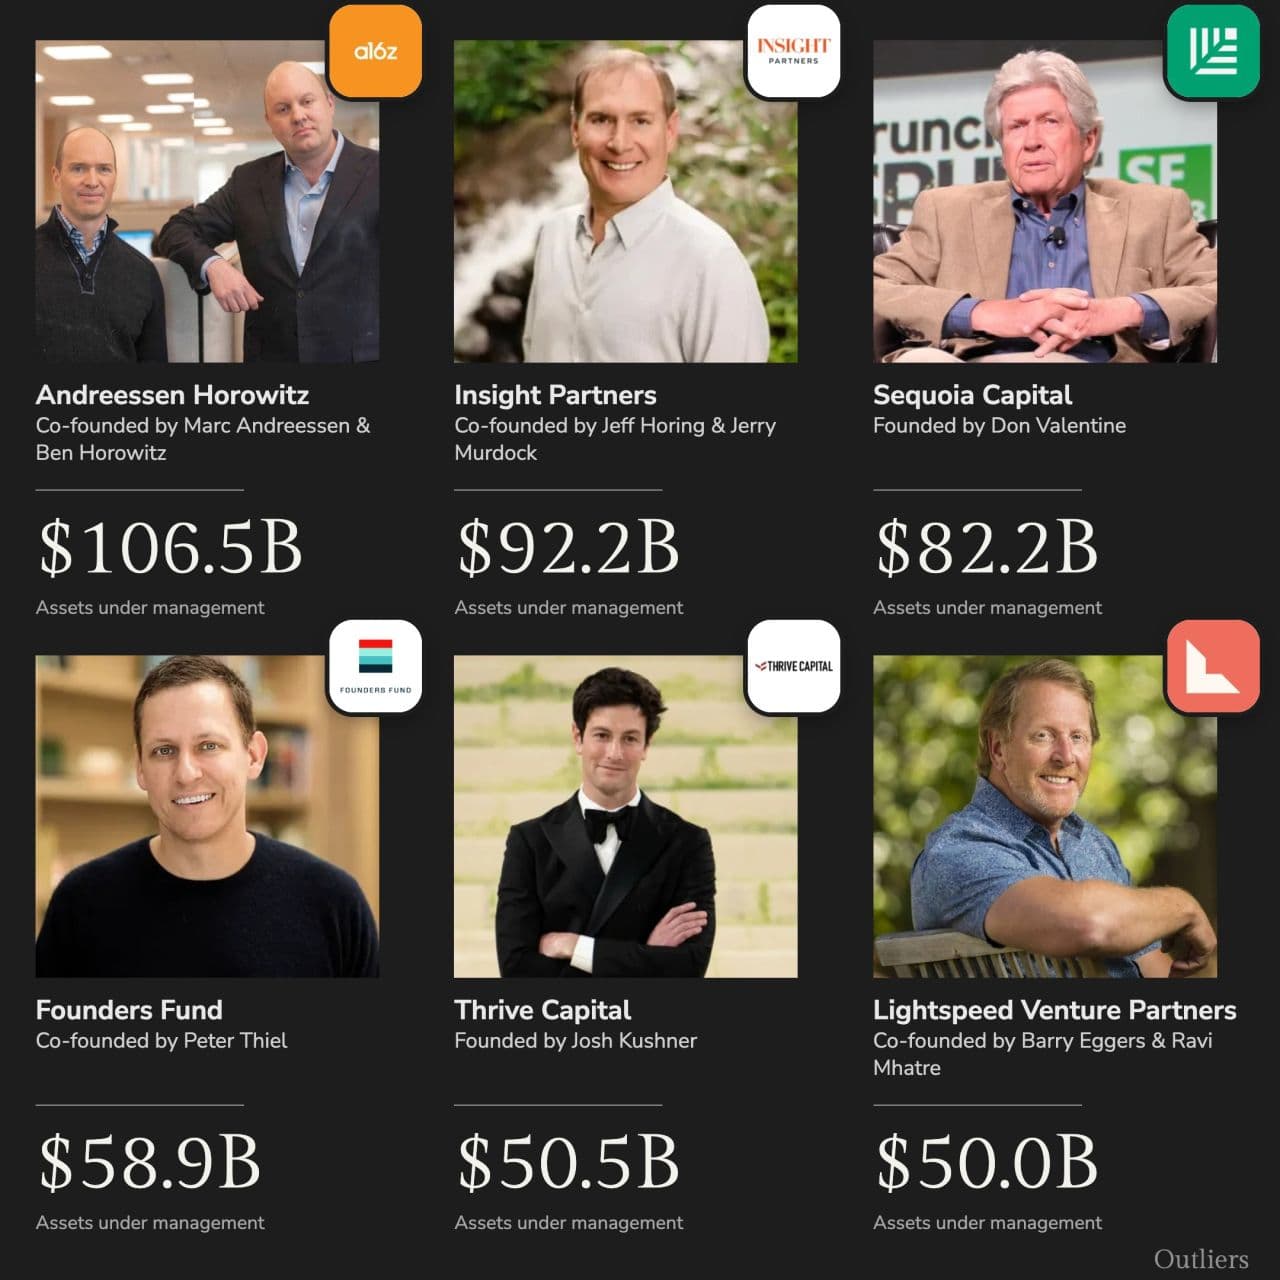
The 6 biggest venture platforms by assets under management:
- Andreessen Horowitz: $106.5B
- Insight Partners: $92.2B
- Sequoia Capital: $82.2B
- Founders Fund: $58.9B
- Thrive Capital: $50.5B
- Lightspeed: $50.0B
Together that’s ~$440B with six firms.
But here’s the twist Newcomer points out too. LPs are sitting on huge paper gains and have seen very little cash back. Megafunds are driven by herd behaviour, so the biggest upside may sit in the contrarian bets.
Is venture heading for an oligopoly, or is this the best moment in years to be a small, contrarian fund?
AUM = regulatory AUM from Form ADV filings, incl. uncalled capital. Snapshot as of 2026. Source: Eric Newcomer, Newcomer; PitchBook-NVCA Venture Monitor Q3 2026; Dealroom (Form ADV data).